What Is Coordination of Benefits in Medical Billing?
Coordination of benefits (COB) is the process payers use to decide how costs are split when a patient has more than one health plan. One plan pays first (primary) and the other pays after (secondary). COB exists so the total reimbursement never exceeds 100% of the bill.
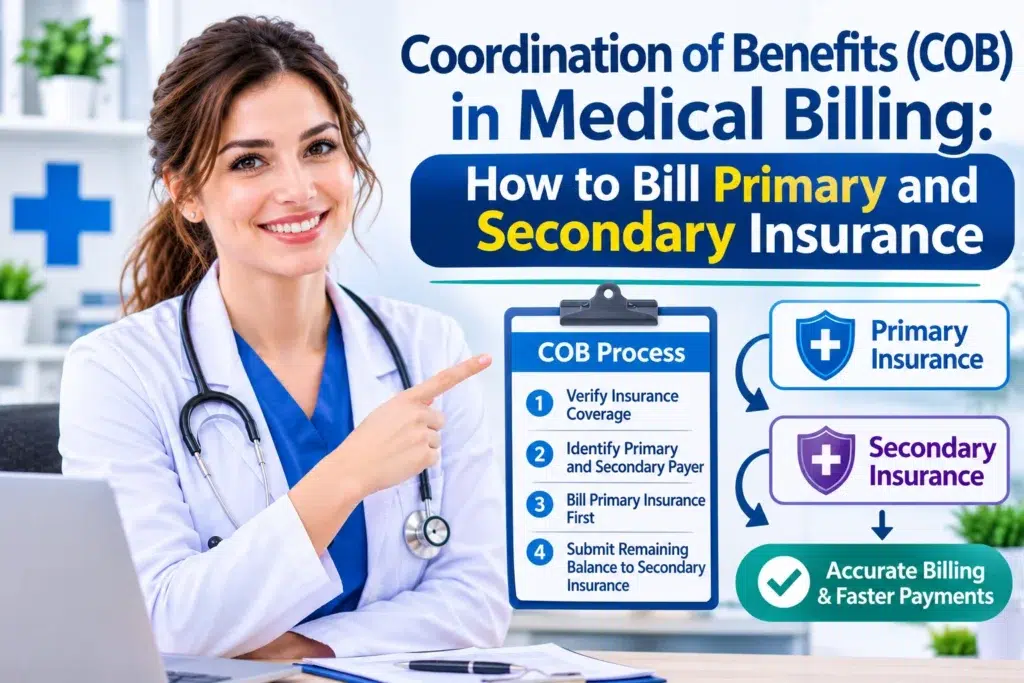
COB meaning in medical billing is that a claim does not end when the primary payer pays. You must confirm the payer order, bill the primary, capture its payment and adjustment data, and then bill the secondary with that data attached. Let’s see how to bill primary and secondary insurance.
COB vocabulary every biller should know
Term | Meaning in practice |
Primary payer | The plan that processes the claim first and pays its normal benefit without regard to other coverage |
Secondary payer | The plan that processes the claim after the primary and considers the remaining patient responsibility |
Tertiary payer | A third plan that considers any balance left after the primary and secondary |
Allowable expense | The amount the plans recognize as eligible for payment, which is not always the provider’s billed charge |
EOB / ERA (835) | The paper or electronic explanation of what the primary payer allowed, paid, and adjusted |
CAS segment | The 837 segment that carries the primary payer’s adjustment group codes, reason codes, and amounts |
MSP | Medicare Secondary Payer: situations where Medicare pays after another insurer |
TPL | Third-party liability: any other person or entity responsible for the patient’s medical costs |
Crossover | The automatic forwarding of a paid claim to a secondary payer, often a Medigap or Medicaid plan |
How Coordination of Benefits Works
COB follows three principles:
- The primary plan pays as if no other coverage exists.
- The secondary plan pays toward what remains, up to its own limits and rules.
- Combined payments cannot exceed the allowed amount.
The three COB calculation methods
Secondary insurance plans use different methods to calculate how much they pay after the primary insurance processes a claim. These methods help you estimate the secondary payment and determine whether the patient owes anything.
Traditional or Standard Method: The secondary payer covers some or all of the remaining balance after the primary insurance pays. It will not pay more than it would have paid if it were the primary insurer. This method often leaves the patient with little or no out-of-pocket cost.
Non-Duplication (Carve-Out) Method: The secondary payer first calculates how much it would normally cover, then subtracts the amount paid by the primary insurance. If the primary payment is higher, the secondary can pay nothing. So, with this option the patient sees a higher remaining balance.
Maintenance of Benefits (MOB) Method: The secondary payer calculates payment using its own allowed amount and subtracts what the primary insurance has already paid. The final payment depends on the plan’s rules and coverage limits, so the patient’s remaining balance can vary.
Worked example
A patient has a commercial primary plan and a commercial secondary plan.
- Billed charge: $300
- Primary allowed amount: $220. Primary pays 80% = $176. Patient responsibility under primary (20% coinsurance) = $44. Contractual write-off = $80.
- Secondary allowed amount: $240. Its normal benefit at 80% would be $192.
The secondary insurance payment depends on its calculation method:
Traditional COB
The secondary plan compares its normal benefit (192) with the remaining patient balance(44). Since the remaining balance is lower, it pays $44. The patient owes nothing.
Non-Duplication COB
The secondary plan subtracts the primary payment (176) from its normal benefit (192). It pays only $16, leaving the patient responsible for the remaining $28.
You can see both methods process the same claim but the patient’s responsibility changes. Under traditional COB, the patient pays $0, while under non-duplication, the patient pays $28. This is why billing staff should read the secondary plan’s COB clause before posting a patient balance.
This is just an example. Actual payment calculations vary depending on the payer’s COB rules and insurance contract. Some coordinate to the lowest allowable and some to the higher, so confirm each contract.
Who Pays First? Primary vs Secondary Insurance Rules
Most commercial plans follow the NAIC Coordination of Benefits Model Regulation, which most states have adopted. Plans generally track those model rules through state requirements or plan terms written to mirror them. The rules run in order and the first rule that settles the question decides it.
Rules for Determining Primary Insurance
- A patient is the subscriber on one plan and a dependent on another: The plan covering the patient as an employee or subscriber pays first.
- Child covered by both parents: The birthday rule usually applies. The plan of the parent whose birthday comes earlier in the calendar year is primary.
- Child of divorced or separated parents: The court order determines which parent’s plan pays first, if one exists. Otherwise, the custodial parent’s plan is usually primary.
- Active employee vs. COBRA or retiree coverage: The active employee’s insurance pays first while COBRA or retiree coverage pays second.
- No other rule applies: The plan that has covered the patient longer usually pays first.
- If the order is still unclear: The plans may share the costs according to the applicable COB rules.
What is the birthday rule?
The birthday rule compares month and day only, never the year of birth and gender is no longer used. Example: if the mother’s birthday is March 15 and the father’s is September 22, the mother’s plan is primary for the children. If both parents share a birthday then the plan that has been in force longer is primary.
Divorced parents: A court decree that assigns responsibility overrides the birthday rule. With joint custody and no decree, the birthday rule applies.
Medicare Secondary Payer (MSP) Rules
Medicare is not always the primary insurance. Federal Medicare Secondary Payer (MSP) rules under Section 1862(b) of the Social Security Act determine whether Medicare or an employer group health plan (GHP) pays first.
The following rules cover the most common situations:
- Age 65 or older with active employment: If the patient or their spouse is still working for an employer with 20 or more employees, the employer’s health plan pays first and Medicare pays second.
- Age 65 or older with a small employer: If the employer has fewer than 20 employees, Medicare usually pays first, and the employer’s health plan pays second.
- Medicare due to disability (under age 65): If the employer has 100 or more employees, the group health plan pays first. If the employer has fewer than 100 employees, Medicare generally pays first.
- End-Stage Renal Disease (ESRD): The employer’s group health plan pays first during the first 30 months of Medicare ESRD eligibility or entitlement. After this period, Medicare usually becomes primary.
Three details are easy to miss:
- COBRA and retiree coverage: The MSP rules do not apply to COBRA or retiree plan coverage for age-based or disability-based Medicare. For those groups, Medicare is generally primary. The ESRD coordination period is the exception, and COBRA can be primary during it.
- Dual entitlement: A patient entitled to Medicare through ESRD and later through age or disability is in a dual-entitlement situation, which needs its own review.
- Ask at every visit. Employment changes, retirement, and a spouse’s job change can all flip the order mid-treatment.
Medicaid, TRICARE, Workers’ Comp, and Auto Insurance
Medicaid
Medicaid pays after other insurance plans including Medicare and commercial insurance. Providers must bill other insurers first and report their payments before sending the claim to Medicaid. If Medicaid does not pay anything extra, providers then cannot bill patients for the remaining balance. But always check your state’s Medicaid billing rules because requirements can vary.
TRICARE
TRICARE usually pays after other health insurance. When TRICARE is the secondary payer, providers must submit the primary insurance payment details with the claim. If the primary insurer pays nothing then include the reason for the non-payment so TRICARE can process the claim correctly.
Workers’ Compensation, Liability, and Auto Insurance
Workers’ compensation, liability, and no-fault auto insurance usually pay before Medicare for covered injuries. Commercial insurance plans can also exclude work-related injuries. When registering a patient after an accident or workplace injury, collect:
- Date of the accident or injury
- Insurance claim number
- Adjuster’s name and contact information
- Insurance company’s mailing address
Denial codes such as CARC 20 (liability insurance) and CARC 21 (no-fault insurance) indicate that another insurance company is responsible for payment.
How to Bill Primary and Secondary Insurance: Step by Step
Collect insurance information at scheduling and check-in
Get front and back copies of all insurance cards. Collect the subscriber’s name, date of birth, employer and relationship to the patient. Ask if the patient has any other coverage through a spouse, parent, or former employer. Ask this at every visit.
Verify eligibility for each insurance plan
Check eligibility (270/271) for every plan on the date of service. Confirm the coverage dates, member ID, plan type and any other insurance information.
Determine which insurance pays first
Follow the rules to decide the payer order, including subscriber before dependent, active coverage before COBRA or retiree coverage, the birthday rule, court orders and Medicare MSP rules. Record how you determined the order.
Update the practice management system
Enter all insurance plans in the correct order: primary, secondary and tertiary. Make sure the subscriber details for each plan are correct.
Submit the claim to the primary payer
Send a complete and accurate claim to the primary insurance company first. Do not send the same claim to both payers at the same time.
Post the primary payer's payment
Use the ERA or EOB to record:
- Primary payer’s name and ID
- Allowed and paid amounts
- Adjustment codes (CO, PR, OA)
- Patient responsibility including deductible, coinsurance and copay
- Claim processing date
Check if the remaining balance should go to the secondary payer
If the primary payer covers the full amount and nothing remains, you do not need to send another claim. If a covered balance or patient responsibility remains, submit the claim to the secondary payer. For Medicare MSP claims, follow the required filing rules even if no additional payment is expected.
Submit the claim to the secondary payer
Include the primary payer’s payment and adjustment details. Submit an electronic 837P claim with the correct COB information or attach the primary EOB when submitting a paper claim.
Post the secondary payment and calculate the patient balance
Record the secondary payer’s payment and adjustments. After all payers have processed the claim, calculate the remaining patient balance. Bill the patient only for the amount allowed under your insurance contracts.
Follow up on both claims
Track primary and secondary claims separately. Check their status regularly and follow up on delays or denials. Remember that waiting for the primary payer can put the secondary claim at risk of missing its filing deadline.
Claim Form and EDI Fields for Secondary Billing
Paper CMS-1500 (02/12)
Box 11d is marked Yes when another health benefit plan exists. Boxes 9, 9a, and 9d carry the other insured’s name, policy or group number, and plan name. Box 29 carries the amount already paid. Payers differ on how they want primary and secondary information on paper claims, so check each payer’s instructions.
Electronic 837P (Professional Claims)
- Payer responsibility: Loop 2000B SBR01 = S for the secondary payer and Loop 2320 SBR01 = P for the primary payer.
- Other payer details: Loop 2330B includes the primary payer’s name and ID.
- Subscriber details: Loops 2320 and 2330A include information about the other subscriber.
- Primary payer payment: Loop 2320 AMT01 = D shows the amount paid by the primary payer.
- Line-level payment: Loop 2430 SVD02 reports the primary payer’s payment for each service line.
- Adjustments: CAS segments show adjustments made by the primary payer.
- Adjudication date: Loop 2330B DTP reports the date the primary payer processed the claim.
Balancing rule: Payers expect the claim-level and line-level numbers to reconcile. For Medicare MSP claims, the sum of line-level primary paid amounts, adjusted by claim-level CAS amounts, must equal the claim-level primary paid amount. Unbalanced COB data is a common reason secondary claims are rejected at the clearinghouse.
Zero-pay primary: If the primary paid $0, one payer’s guidance says the CAS02 field should carry the reason code for the non-payment.
Special case, multiple primaries on Medicare: Claims with multiple primary payers cannot be sent electronically to Medicare, and a hard-copy CMS-1500 must be submitted instead.
How M&M Claims Care Helps With COB and Secondary Billing
COB errors are among the most preventable causes of denied and delayed claims. At M&M Claims Care, we support practices with insurance verification, payer-order checks, primary and secondary claim submission, denial follow-up, and accounts receivable recovery. Contact M&M Claims Care to review where COB is slowing your collections.